Solidigm pivots to US fab abandons IPO
In a shifting landscape where the semiconductor industry is constantly redefining the boundaries of technology and finance, major players are forced to recalibrate their strategies. SK hynix, a titan in the memory space, recently made a significant strategic pivot regarding its U.S. enterprise SSD subsidiary, Solidigm, opting to shelve plans for an initial public offering (IPO).
This decision was not taken lightly, but it reflected a pragmatic response to the current economic climate. Facing volatile stock market conditions and challenging semiconductor share price trends, the company determined that pursuing an IPO would not yield the optimal financial outcome necessary to fund its ambitious expansion goals.
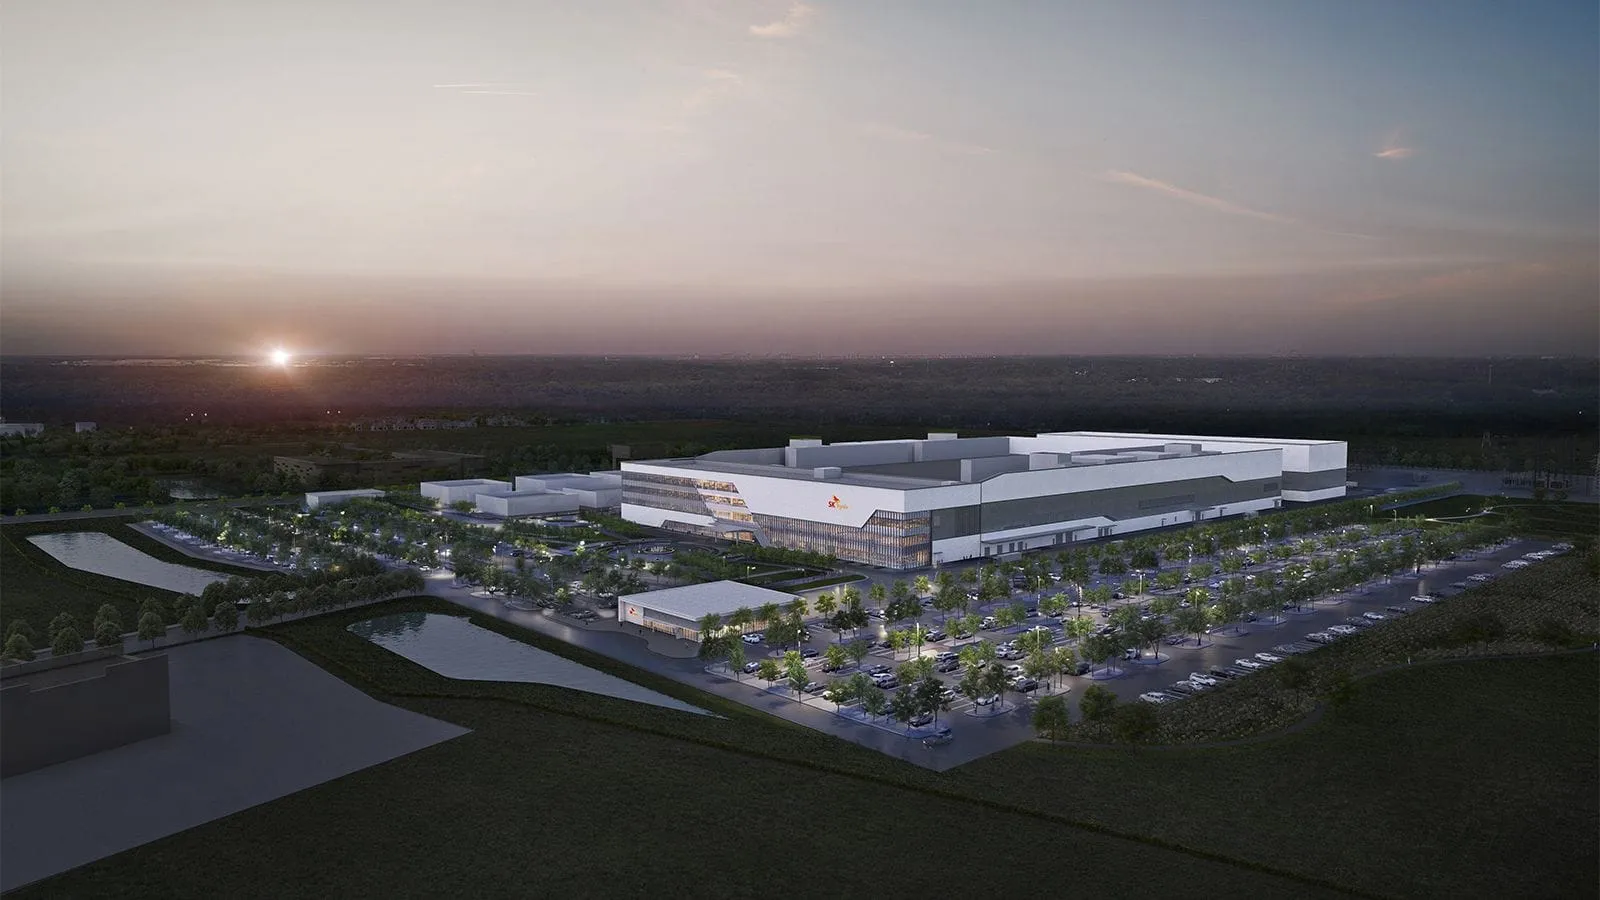
Instead of seeking external financing, SK hynix has doubled down on its commitment to growth by confirming plans to build a new fabrication facility for Solidigm in the United States. This move directly addresses the surging demand for high-capacity enterprise SSDs, positioning the subsidiary to capitalize on the accelerating AI infrastructure buildout.
The real question, however, lies in the financing of this monumental undertaking. Constructing a modern 3D NAND fab requires staggering capital, and while an IPO could have provided billions in external funds, the company opted for a more internally driven strategy. This shift signals a focus on preserving capital for other critical projects while maintaining full control over the subsidiary’s trajectory.
This approach is underpinned by an assessment of Solidigm’s exceptional financial health. The subsidiary operates in a highly specialized niche, controlling a significant portion of the enterprise SSD market. With related entities demonstrating extraordinary profit margins, SK hynix believes that the operations of Solidigm generate substantial internal cash flow.
For instance, the enterprise storage division of a major competitor recently reported remarkably high non-GAAP gross margins. Given Solidigm’s unique market position and the exclusive products it controls, these margins are likely even more compelling. This strong profitability suggests that Solidigm can substantially contribute to SK hynix’s consolidated earnings, potentially allowing the company to finance the U.S. expansion through internal resources and debt, avoiding ownership dilution.
Ultimately, the decision showcases a strategic prioritization: rather than monetizing a subsidiary at a valuation deemed insufficient in the current environment, SK hynix is leveraging its existing strength and profitable operations to drive its manufacturing footprint forward. It is a clear demonstration that strategic growth in the semiconductor space is often best fueled by internal strength and strategic alignment, rather than relying solely on public market timing.
Buy on Amazon
Credit
