Scammers used USB drives to steal $230m in crypto from Poland for oil deal
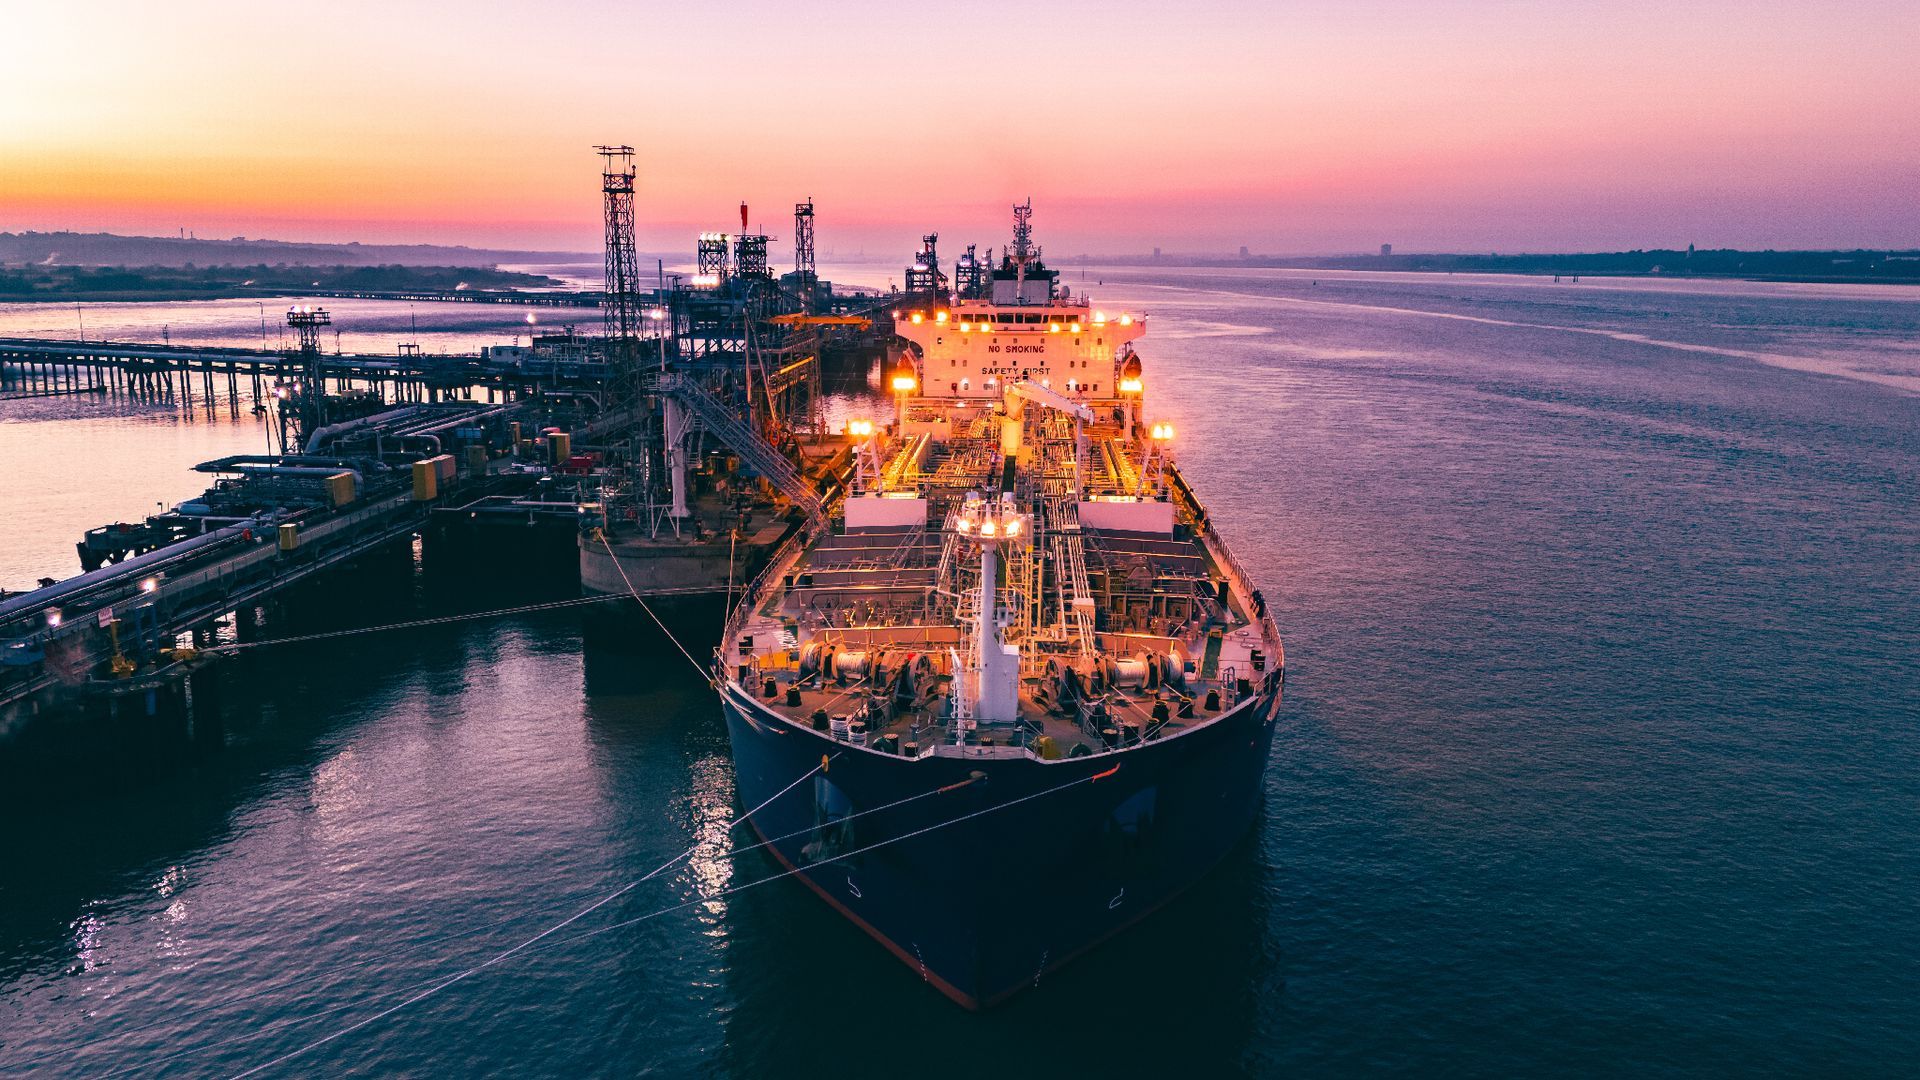
Despite the lingering shadow of international sanctions, Venezuela remains a source of immense oil wealth, a reality that continues to attract serious buyers. Yet, navigating this global market is an exercise in high-stakes complexity, especially when dealing with massive energy transactions and the evolving world of digital finance.
In 2023, a major player, Poland’s state-backed Orlen energy group, sought to acquire millions of barrels of Venezuelan crude. Seeking an avenue outside traditional banking constraints, this group opted to use the promise of the USDT stablecoin cryptocurrency—a system where 1 USD equals 1 USDT—as a mechanism for the transaction.
The plan involved setting up a convoluted series of international exchanges and shell companies. An external firm facilitated the deal, leveraging UK services and Dubai-based entities to move staggering sums. The ambition was to convert vast amounts of fiat into crypto, but the execution quickly spiraled into a labyrinth of uncertainty and missing funds.
The financial journey was fraught with setbacks. While one transfer successfully moved $80 million into USDT, the overall operation encountered significant losses. Much of the funds vanished, resulting in an estimated $230 million unaccounted for across multiple stages of the process. The net position for the deal quickly turned into a significant deficit.
Adding to the complexity, the physical delivery of the oil involved weeks of delays while three Polish tankers waited at Venezuelan ports, incurring enormous demurrage fees. The timeline suffered, pushing the entire scheme further into the realm of speculation and risk.
To manage the physical exchange, representatives traveled to Venezuela, moving physical USDT stored in various cold wallets. These representatives navigated a confusing landscape of local energy companies and brokers, some of whom proved to be little more than conduits, complicating any attempt at formal verification.
The transaction culminated in a series of exchanges with local entities, followed by promises of delivery that ultimately failed to materialize. Despite some partial recovery of funds from the Dubai exchanges, the overall financial picture remained devastating. The cumulative losses and associated costs tied to the entire operation were estimated to reach $424 million.
This massive financial entanglement highlights a critical systemic flaw: the promise of blockchain transparency does not automatically equate to total accountability. The failure was not in the technology itself, but in the missing link between digital assets and real-world legal identities. Reputable financial systems require identity verification, or Know Your Customer (KYC), to establish ownership. In this case, the absence of verifiable records linking crypto wallets to specific persons or entities created an impenetrable shield for those involved.
Ultimately, while the on-chain ledger reveals the flow of digital currency, it cannot conjure the missing legal paperwork. The lack of official records allowed those facilitating the transactions to vanish, leaving investigators with an almost insurmountable burden of proof. This saga serves as a stark reminder that in the high-stakes world of global finance, the absence of traceable legal identities can be just as powerful as any digital encryption.
Buy on Amazon
Credit